Cardiff Prime Office Rents Surge 34% to £33.50 as Grade A Space Availability Plummets
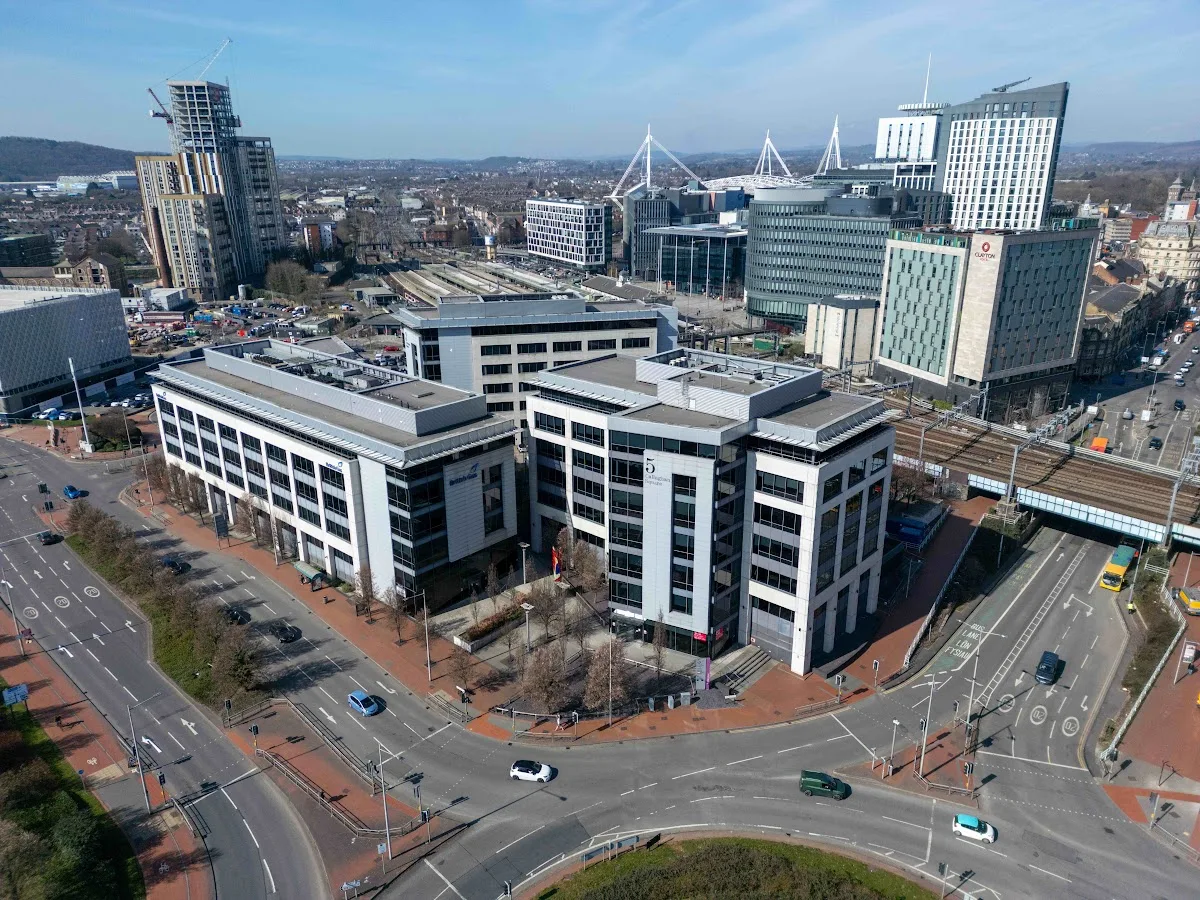
Cardiff prime office rents have surged by 34% over the past two years, reaching £33.50 per square foot. This sharp increase nearly doubles the 18% average rise seen across the UK’s ten largest office markets outside London. New analysis from Knight Frank confirms the Welsh capital is outpacing most regional rivals in rental growth.
The independent commercial property consultancy’s research highlights a dramatic shift in the market. After remaining static at £25 per square foot for seven consecutive years, rents in the Welsh capital have climbed substantially in the last 24 months. Only Leeds recorded a larger percentage increase during this specific period.
While the overall vacancy rate for office accommodation in Cardiff stands at 12.1%, availability of Grade A space has plummeted. In the last quarter, availability of the highest-quality space fell to just 1.5%. Knight Frank forecasts this trend will continue, with no new-build developments currently expected on site.
Demand for the best office space remains resilient despite the limited supply. In the first three quarters of 2026, there was 376,388 square feet of take-up across 76 deals. This activity puts Cardiff on track to exceed the city’s long-term annual average of 460,000 square feet.
Nearly three-quarters (72%) of the total take-up was located in the city centre. Professional services occupiers have been particularly active in pursuing prime offices close to Central Station. Firms including Acuity Law, Knights, and Ridge have been prominent in securing these prime locations.
Three major refurbishment schemes are currently on the horizon for the city. These include the restoration of the Brains Brewery Building at Central Quay and the full refurbishment of No. 4 Callaghan Square.
The repurposing of the former Howells department store is also part of this development pipeline.
Combined, these projects could add close to 300,000 square feet to the city’s office stock. Knight Frank stated that with these schemes coming to market, live requirements and diminishing supply will drive prices up. Prime rents could reach £35 per square foot by the end of the year.
The consultancy predicts rents may push closer to £40 per square foot through Q1 2027. The next new building at 1 Central Quay has planning for 160,000 square feet south of Central Station. However, this project will require a significantly higher rent and substantial pre-letting to become viable.
Mark Sutton, office agency partner at Knight Frank Cardiff, provided insight into the current market conditions. He noted that prime office rents in Cardiff have held firm at £33.50 per square foot in Q3. Quoting levels for the best space are now reaching £37.50 per square foot.
Sutton explained: “The city’s lack of stock means we expect prime rents to rise further through Q4 and into 2027.” Incentives have remained stable but are tightening where availability is limited, particularly for prime space and larger or bespoke requirements.
He observed a similar pattern emerging across the UK’s regional cities in recent years. Prime space in Bristol broke through £50 per square foot in 2025 and now reaches £55 per square foot. Cardiff still trails these markets at a headline level but has gained significant momentum.
Sutton added: “As rents rise, there is sustained demand and very limited availability of the best-quality office space.” Landlord-delivered, fully fitted space is a growing trend in the Cardiff market. In recent years, there have been far fewer deals involving fitted accommodation than in other UK cities.
He continued: “But as capital costs continue to rise, and tenants are generally less willing to commit to long-term leases, these fitted solutions become more attractive to occupiers.” As a result, we are seeing more landlords opt to invest in delivering ‘plug and play’ space in return for higher rents and offsetting rent-free incentives.
Tom Griffiths, capital markets associate at Knight Frank Cardiff, commented on the investment implications. He stated: “The movement in prime rents has been significant from a capital markets perspective.” For the first time in years, viable rental growth is coming through on first-generation, Grade A offices, driven by the lack of supply and a clearer path to higher headline rents.
Griffiths concluded: “That’s creating conditions where pre-lets on refurbishments are now realistic.” The market is pointing in the right direction. Investors who previously struggled to make the numbers stack up are finding that rising rents, tightening incentives, and solid fundamentals in the city centre are making well-located assets in Cardiff an attractive proposition – and that can only be positive for investment in the city.